Seminário de Pesquisa 27/08
Deixe um comentário / Economia Aplicada, Seminários de Pesquisa / Por Helena Camillo
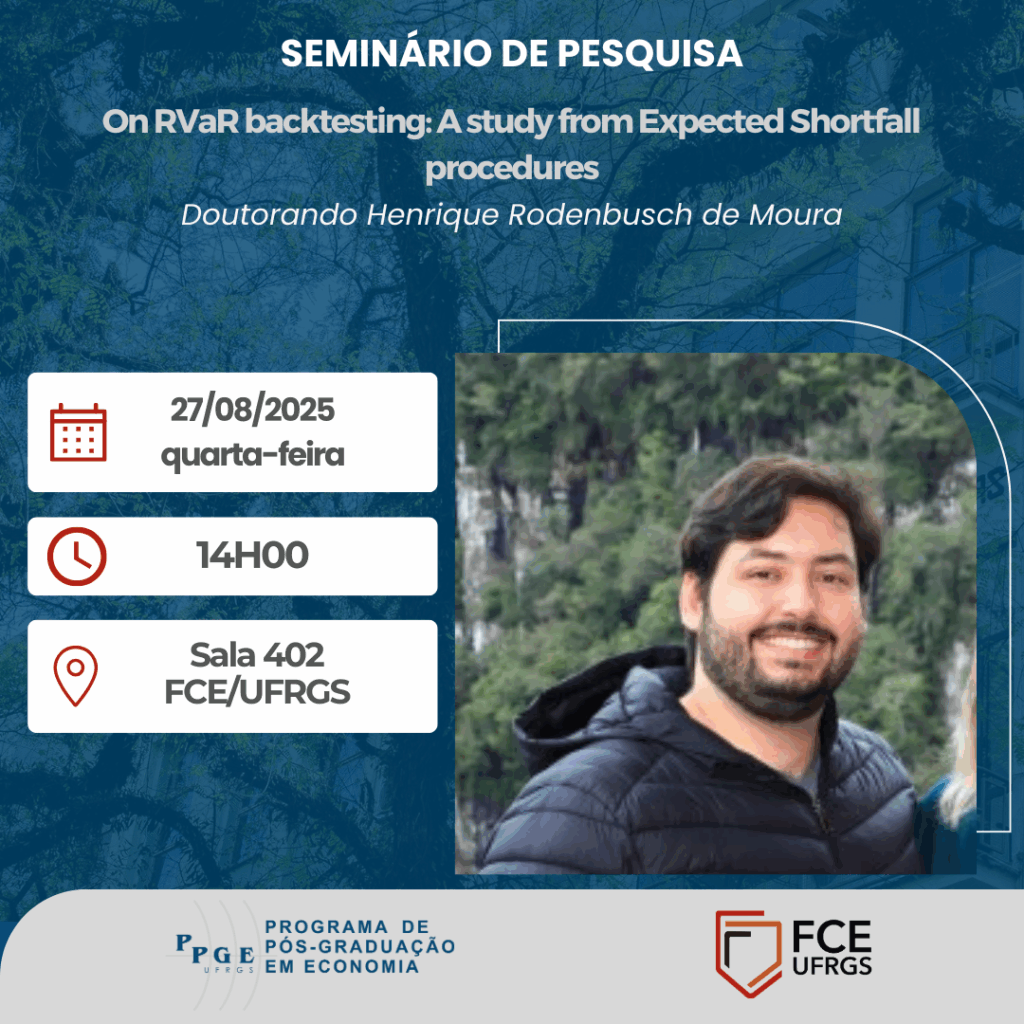
Ocorrerá no dia 27/08/2025, quarta-feira, às 14h na sala 402 – FCE, o Seminário de Pesquisa “On RVaR backtesting: A study from Expected Shortfall procedures”, na área de Economia Aplicada, ministrado pelo Doutorando Henrique Rodenbusch de Moura (UFRGS).
Resumo:
This paper refines Expected Shortfall (ES) backtesting definitions using exceedance residuals to improve effectiveness in evaluating risk forecasts of Range Value-at-Risk (RVaR). We analyze the statistical size and power properties of the backtests across different scenarios using Monte Carlo simulations and apply them to real financial data. We also integrate the RVaR loss function to assess the empirical consistency of both methods. No single backtesting approach consistently outperforms the others in numerical and empirical analyses. The statistical power of the tests deteriorates as the out-of-sample size increases. However, within-sample observations enhance size stability and improve power, particularly for normally distributed data at significance levels α = 1% and β = 2.5%. For data-generating processes with pronounced third and fourth moments, our procedures exhibit higher power when applied to normal distribution predictions. Empirically, when compared with realized loss, our methods produce similar results under optimal conditions.