Deixe um comentário / Bancas de Tese e Dissertação / Por Helena Camillo
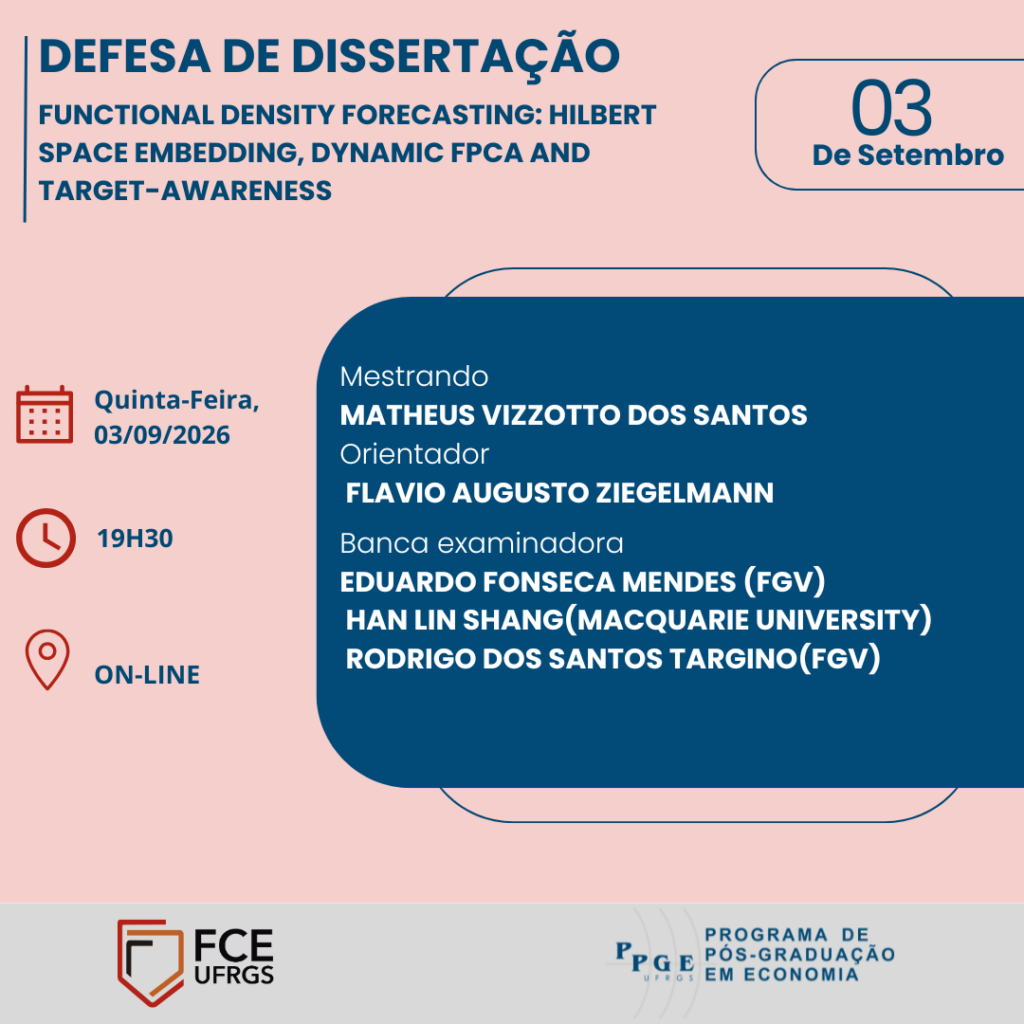
Functional Density Forecasting: Hilbert space embedding, dynamic fPCA and target-awareness
Resumo:
Functional Data Analysis (FDA) has emerged as a rapidly evolving field, extending classical statistical methods to data represented by functions. In this context, time-dependent analysis can also be generalized by treating each observation as a function rather than a scalar or vector, giving rise to functional time series. This work focuses on forecasting a specific class of functional objects: probability density functions (pdfs). A key challenge in this setting arises from the fact that pdfs do not form a vector space, but instead reside in a convex subset, rendering standard functional time series techniques a tricky endeavor. To address this, a transformation approach that maps these objects into a Hilbert space is used, which enables the application of established functional time series tools. One of the main theoretical contributions is the definition of an appropriate forecasting target. Since nonparametric density estimators are inherently biased, forecasting the transformed estimated density is generally not equivalent to forecasting the transformed latent density; we therefore propose a target-aware formulation that explicitly accounts for the estimation step. We then provide a complex simulation exercise by introducing GAS dynamics for the transformed pdfs. Finally, our empirical exercise focuses on financial risk forecasting, where we particularly study realized volatility.
Local: Online, através deste link.